The apple pie approach to tax diversification and retirement income planning
October 30, 2026
Kayleigh Tuenge
Wealth Advisor
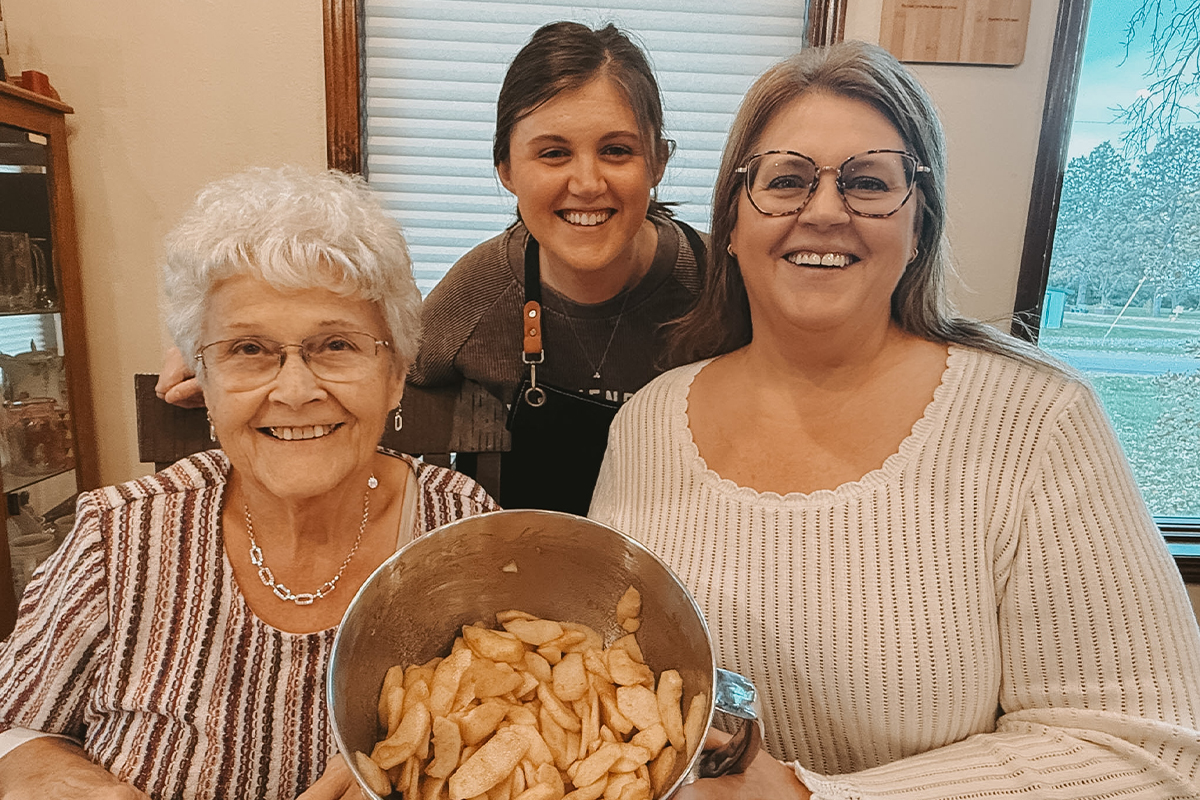
Fall has always been a favorite season for me, especially when it means a trip to the orchard to pick apples and then heading home to make pies with my mom and grandma.
From choosing the perfect apples and rolling out the crust to filling the kitchen with the smell of cinnamon and baked apples, it became one of my most cherished fall traditions.
One thing I learned early: the best pies are made with more than one type of apple.
A firm apple holds its shape, so every slice has texture.
A sweet apple adds warmth.
A tart apple brings brightness.
Put all three together, and the pie is richer, more balanced, and more satisfying than any one apple could be on its own.
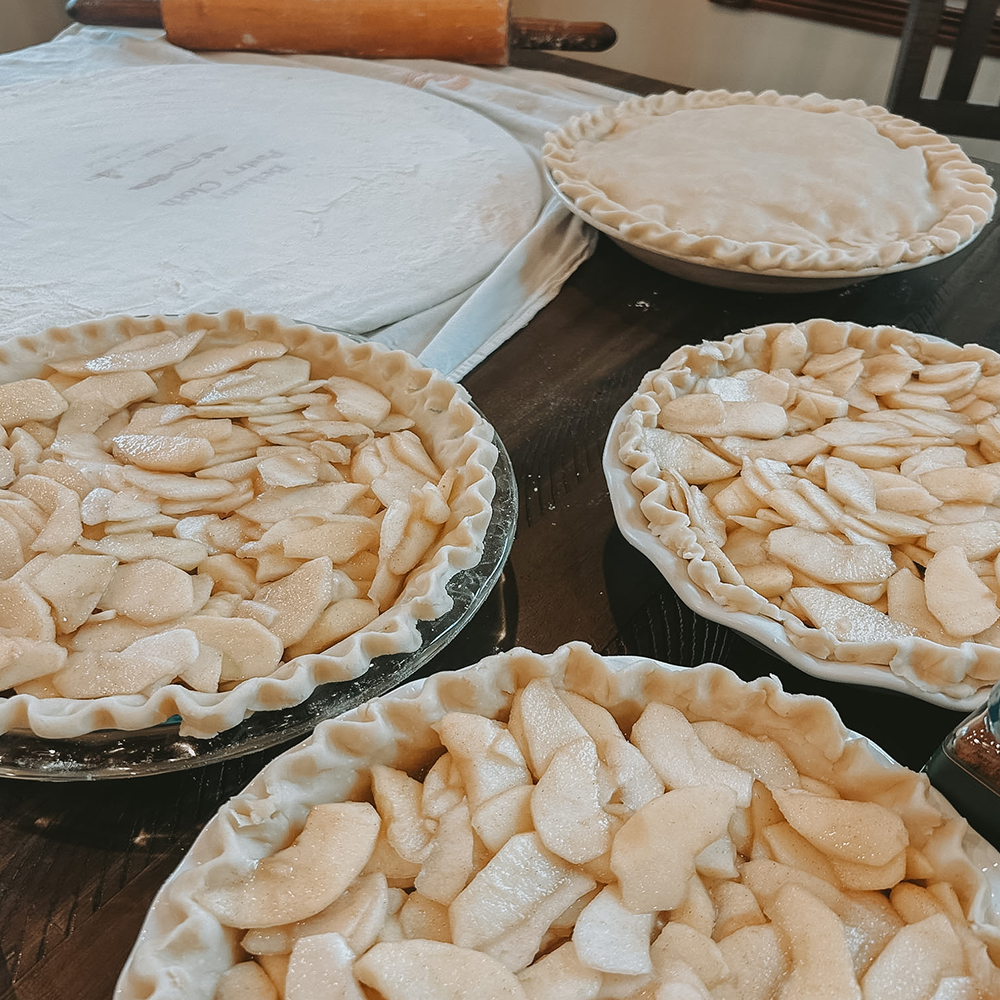
Retirement income planning can work the same way; just as a great apple pie benefits from a blend of different apples, a retirement strategy can benefit from a mix of account types.
What is tax diversification?
In retirement planning, a great apple pie can be compared to a concept known as tax diversification.
Instead of relying on one single account type, it can be helpful to build three different “buckets” of money: a tax-deferred bucket, a tax-free bucket, and a taxable bucket.
Each bucket serves a different purpose and offers unique tax advantages.
Together, they can provide greater flexibility when taking distributions, managing your retirement tax bill, and supporting your estate planning goals.
The first apple: The tax-deferred bucket
The tax-deferred bucket includes assets such as traditional IRAs, traditional 401(k)s, and pensions. Taxable portions of Social Security benefits can also contribute to ordinary taxable income.
During your working years, this bucket can provide valuable tax benefits as pre-tax contributions may reduce your current taxable income.
Investments also grow on a tax-deferred basis, allowing earnings to compound without being taxed each year. When funds are withdrawn in retirement, they are taxed as ordinary income.
In the pie analogy, this is the apple that adds structure.
For many individuals, it is the largest apple in the mix and often serves as a primary source of retirement income.
However, over time, it may become the bucket you have the least control over.
Required minimum distributions eventually require withdrawals, and Social Security benefits are paid regardless of whether additional income is needed.
If this is your only bucket, you have less flexibility over when and how income shows up on your tax return.
The second apple: The tax-free bucket
The tax-free bucket may include a Roth IRA or Roth 401(k).
Roth accounts are funded with after-tax dollars, which means you do not receive the same upfront tax deduction you might get with a traditional retirement contribution.
The tradeoff is that qualified withdrawals are tax-free in retirement.
This bucket can be especially valuable because it gives you access to money that, when withdrawn properly, does not increase your taxable income.
This matters in years when you are trying to:
- avoid being pushed into a higher tax bracket
- reduce the taxation of Social Security benefits
- manage Medicare-related income thresholds
- leave assets to heirs in a tax-conscious way
In our pie analogy, this is the apple that adds sweetness.
You pay the tax up front, so later on, this bucket gives you a sweeter source of income when you need it most.
The third apple: The taxable bucket
The taxable bucket usually includes accounts like an individual or joint brokerage account.
These accounts are funded with money you have already paid taxes on, and they do not have the same retirement account rules as an IRA or 401(k).
The benefit of this bucket is flexibility. You do not have to wait until a certain age to access the money, and there are no required minimum distributions.
You may owe taxes on interest, dividends, or gains when investments are sold, but long-term capital gains are typically taxed at a lower rate than ordinary income.
That can make this bucket useful when you want retirement income without automatically increasing ordinary taxable income dollar for dollar.
In the pie, this is the apple that adds brightness. It gives you room to maneuver.
Need to fund a home project, cover a larger expense, or bridge the gap before Social Security or required distributions begin?
A taxable account can help provide that flexibility.
Why the best retirement pie uses all three: The importance of tax diversification
Maintaining a mix of tax-deferred, tax-free, and taxable accounts can provide greater flexibility when managing income and taxes in retirement.
Relying solely on one account type can limit your options and create tradeoffs, whether that means higher taxable income, fewer tax deductions, or less tax-advantaged growth.
When you have all three buckets, you can choose the right “apple” for the situation.
In some years, it may make sense to draw more from a traditional IRA or consider a Roth conversion.
In others, Roth or taxable accounts may help manage taxable income.
For those wanting to leave a legacy, Roth accounts can also be an effective wealth transfer tool.
The goal is not to avoid taxes altogether, but to create choices. Retirement can last decades, and tax laws, income needs, market returns, health expenses, and family goals can all change along the way.
A tax-diversified plan gives you more ingredients to work with.
Bringing it back to the kitchen
When my mom and grandma made apple pie, they were not choosing three apples just to make the recipe more complicated.
They were choosing each apple because it had a job to do. Your retirement accounts can work the same way.
A thoughtful mix of accounts provides greater flexibility, allowing you to make the most of your retirement income.
If you’re wondering whether your retirement savings has the right balance of tax-deferred, tax-free, and taxable assets, I’d be happy to help.
Reach out to me, and together we can determine whether your retirement “recipe” has the best ingredients to support your long-term goals!
Prepare for what's next
Whatever your next steps are, we can help simplify the journey ahead.
I'm Ready